September 8, 2025
Fund Manager Spotlight: Fusion Fund
Q&A with Lu Zhang, Founder & Managing Partner
General Partner
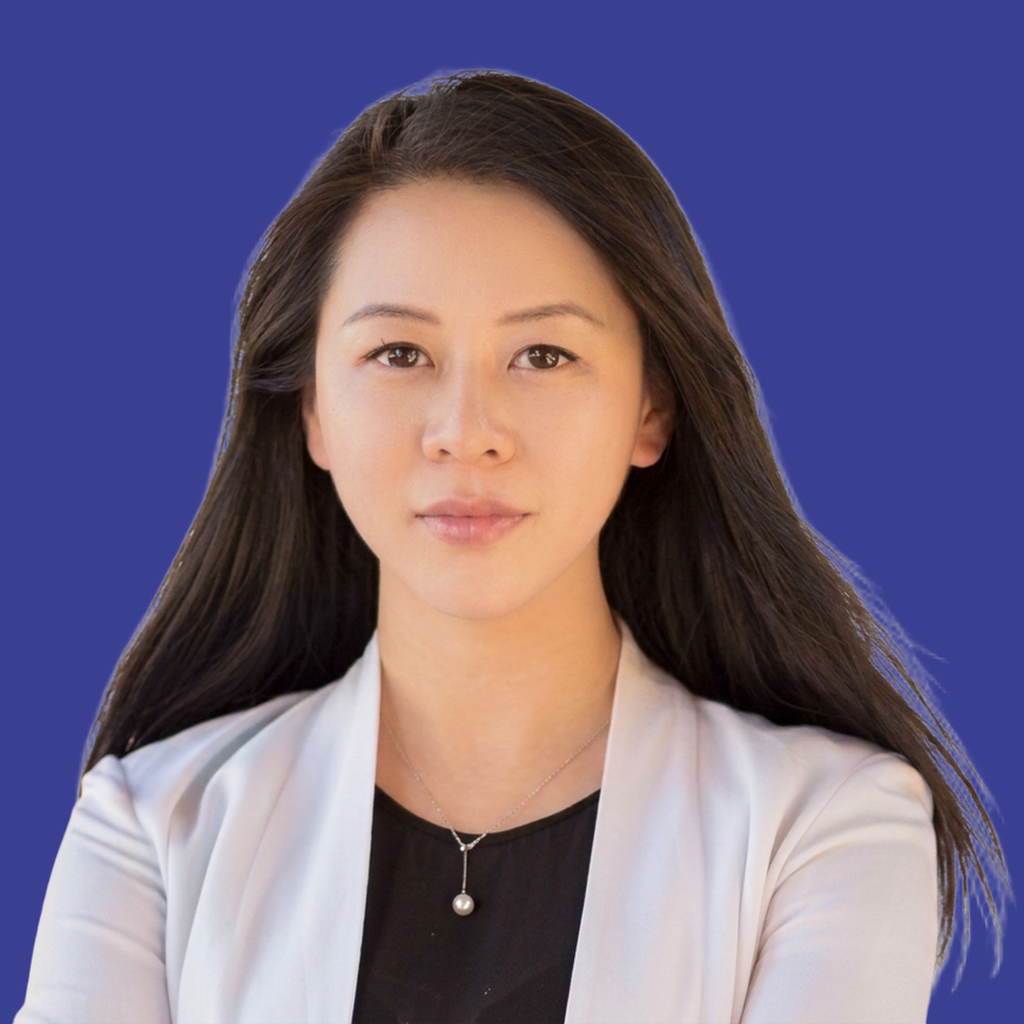
Lu Zhang is Founder and Managing Partner of Fusion Fund, an early-stage venture firm backing companies in enterprise AI, healthcare, and industrial technology. Before founding the fund, she built a medical device company that was later acquired. Rohati General Partner Nick Talwar met Lu at a World Economic Forum leadership workshop at Oxford in 2016. They sat down to discuss her path into venture investing, Fusion Fund's approach, and how it aligns with Rohati's mandate.
You run what we would consider one of the rising leaders among early-stage deep tech funds. Tell us your personal journey and how you got to where you are.
Zhang: I was born and raised in Inner Mongolia and moved to the U.S. in 2010 to pursue a PhD in Materials Science and Engineering at Stanford. At 21, I founded a medical device company focused on type II diabetes testing powered by machine learning, which was later acquired by a leading publicly listed healthcare company. Using the financial returns, I began angel investing in early-stage startups in deep tech and healthcare. This entrepreneurial journey, combined with my investing experience, gave me first-hand insight into the Silicon Valley innovation ecosystem and confirmed my passion for supporting innovations that can change the world. In 2015, I founded Fusion Fund with the mission of backing early-stage founders applying frontier technologies across enterprise AI, healthcare, and industrial automation to transform industries. Since then, we've grown to over $500M in AUM with a disciplined, sector-focused investment approach.
In our world, it's all AI all the time. In your role, how do you separate the wheat from the chaff? What do you invest in and what do you stay away from?
Zhang: AI is an incredibly powerful enabler, but in early-stage investing, technology alone isn't enough. We focus on companies where AI is applied to solve high-value, industry-specific problems where there's a clear path to defensibility and adoption. We value companies with unique access to high-quality, proprietary data, a strong understanding of real market use cases in their industry, and the technical expertise to optimize AI infrastructure to lower the cost of AI solutions and integration for their target clients. This is especially important because all of our investments are in B2B business models, where cost efficiency and deep industry knowledge directly impact adoption. We avoid "AI for AI's sake" and crowded areas with low barriers to entry, such as generic chatbots or thin wrappers around foundational models. Instead, we look for strong technical moats, real market demand, and founders who combine cutting-edge technology with a clear path to business impact.
Will AI change venture investing? More specifically, with the capital efficiency we seem to be seeing from AI-native companies what may that mean for later stage venture funds?
Zhang: Yes, AI is fundamentally reshaping the venture landscape, and the capital efficiency of AI-native companies creates a significant tailwind for our strategy. The AI trend enables founders to build sizable businesses and meaningful revenue with very small teams and limited capital. That means they often require less funding in the future, compressing the traditional funding timeline. As a result, many late-stage VC firms are now trying to invest earlier, at the seed or Series A stage, to secure access to the best opportunities before they scale. However, these later funds are accustomed to evaluating startups on clear traction metrics that are often absent in the early stages. In this new environment, our team's deep technical background as technologists, scientists, and former entrepreneurs is a critical advantage for identifying top companies in their early stages. At Fusion Fund, we've been early adopters, we've had our own AI analyst, Ada, since 2018, and we leverage APIs from our AI portfolio companies to create internal tools and features that significantly boost our productivity. Overall, this shift is positive for early-stage funds like ours, since our capital can take companies further, and our ability to identify high-quality, capital-efficient AI businesses early becomes even more valuable.
Tell us about Fund II and Fund III — why should we be excited about them?
Zhang: Fund II and Fund III have built a concentrated portfolio of category-defining companies in enterprise AI, healthcare, and industrial tech. The portfolio includes hyper-growth companies like You.com in Fund III and Lepton AI, which was recently acquired by NVIDIA. A key advantage of these funds is that many of the initial investments were made when AI was not yet the hot buzzword it is today, which means we entered at much lower valuations. Our model is high conviction, hands-on, and founder-first. We're disciplined in valuation, rigorous in due diligence, and committed to supporting founders beyond capital, from customer introductions to exits. The combination of disciplined entry, high-quality companies, and strong sector tailwinds is why we believe Funds II and III are so exciting.
Enjoyed this piece? We’d love to hear from you.
admin@rohati.capital